Need Help? Call or Text: (918) 420-9999
Need Help? Call or Text: (800) 420-9767
Not a Government Entity
Questions? Call (918) 420-9999
Need Help? Call or Text: (800) 420-9767
"Doesn't Medicare Already Cover This?"
Original Medicare pays a lot, but not all of it. Part A has a deductible for every hospital stay, and Part B leaves you responsible for 20% of most outpatient costs, with no cap on how high that 20% can climb in a bad year. A Medicare Supplement plan is built to pick up exactly what is left, so a bad year does not become a bad decade.
Maybe this sounds familiar:
- Can I really see any doctor, anywhere?
- Why does my neighbor pay a different premium for the same plan letter?
- I missed my enrollment window. Can I still get one?
- Do I need a Part D plan too?
All fair questions, and every one has a clear answer. The sections below cover how these plans actually work, and the things that trip people up most.
How a Medicare Supplement Actually Works
Three things explain almost everything: what it covers, why the plan letter matters more than the company, and when you can buy one without a health question asked.
It works alongside Original Medicare, never instead of it
A Supplement plan does not replace Medicare. It rides behind it. Medicare pays its share first, then your Supplement automatically picks up some or all of what is left: deductibles, coinsurance, copays. You keep both Medicare cards, keep your Part B premium, and add one monthly premium for the Supplement itself. Drug coverage is not built in; that stays a separate Part D plan.
Every company sells the same standardized plans
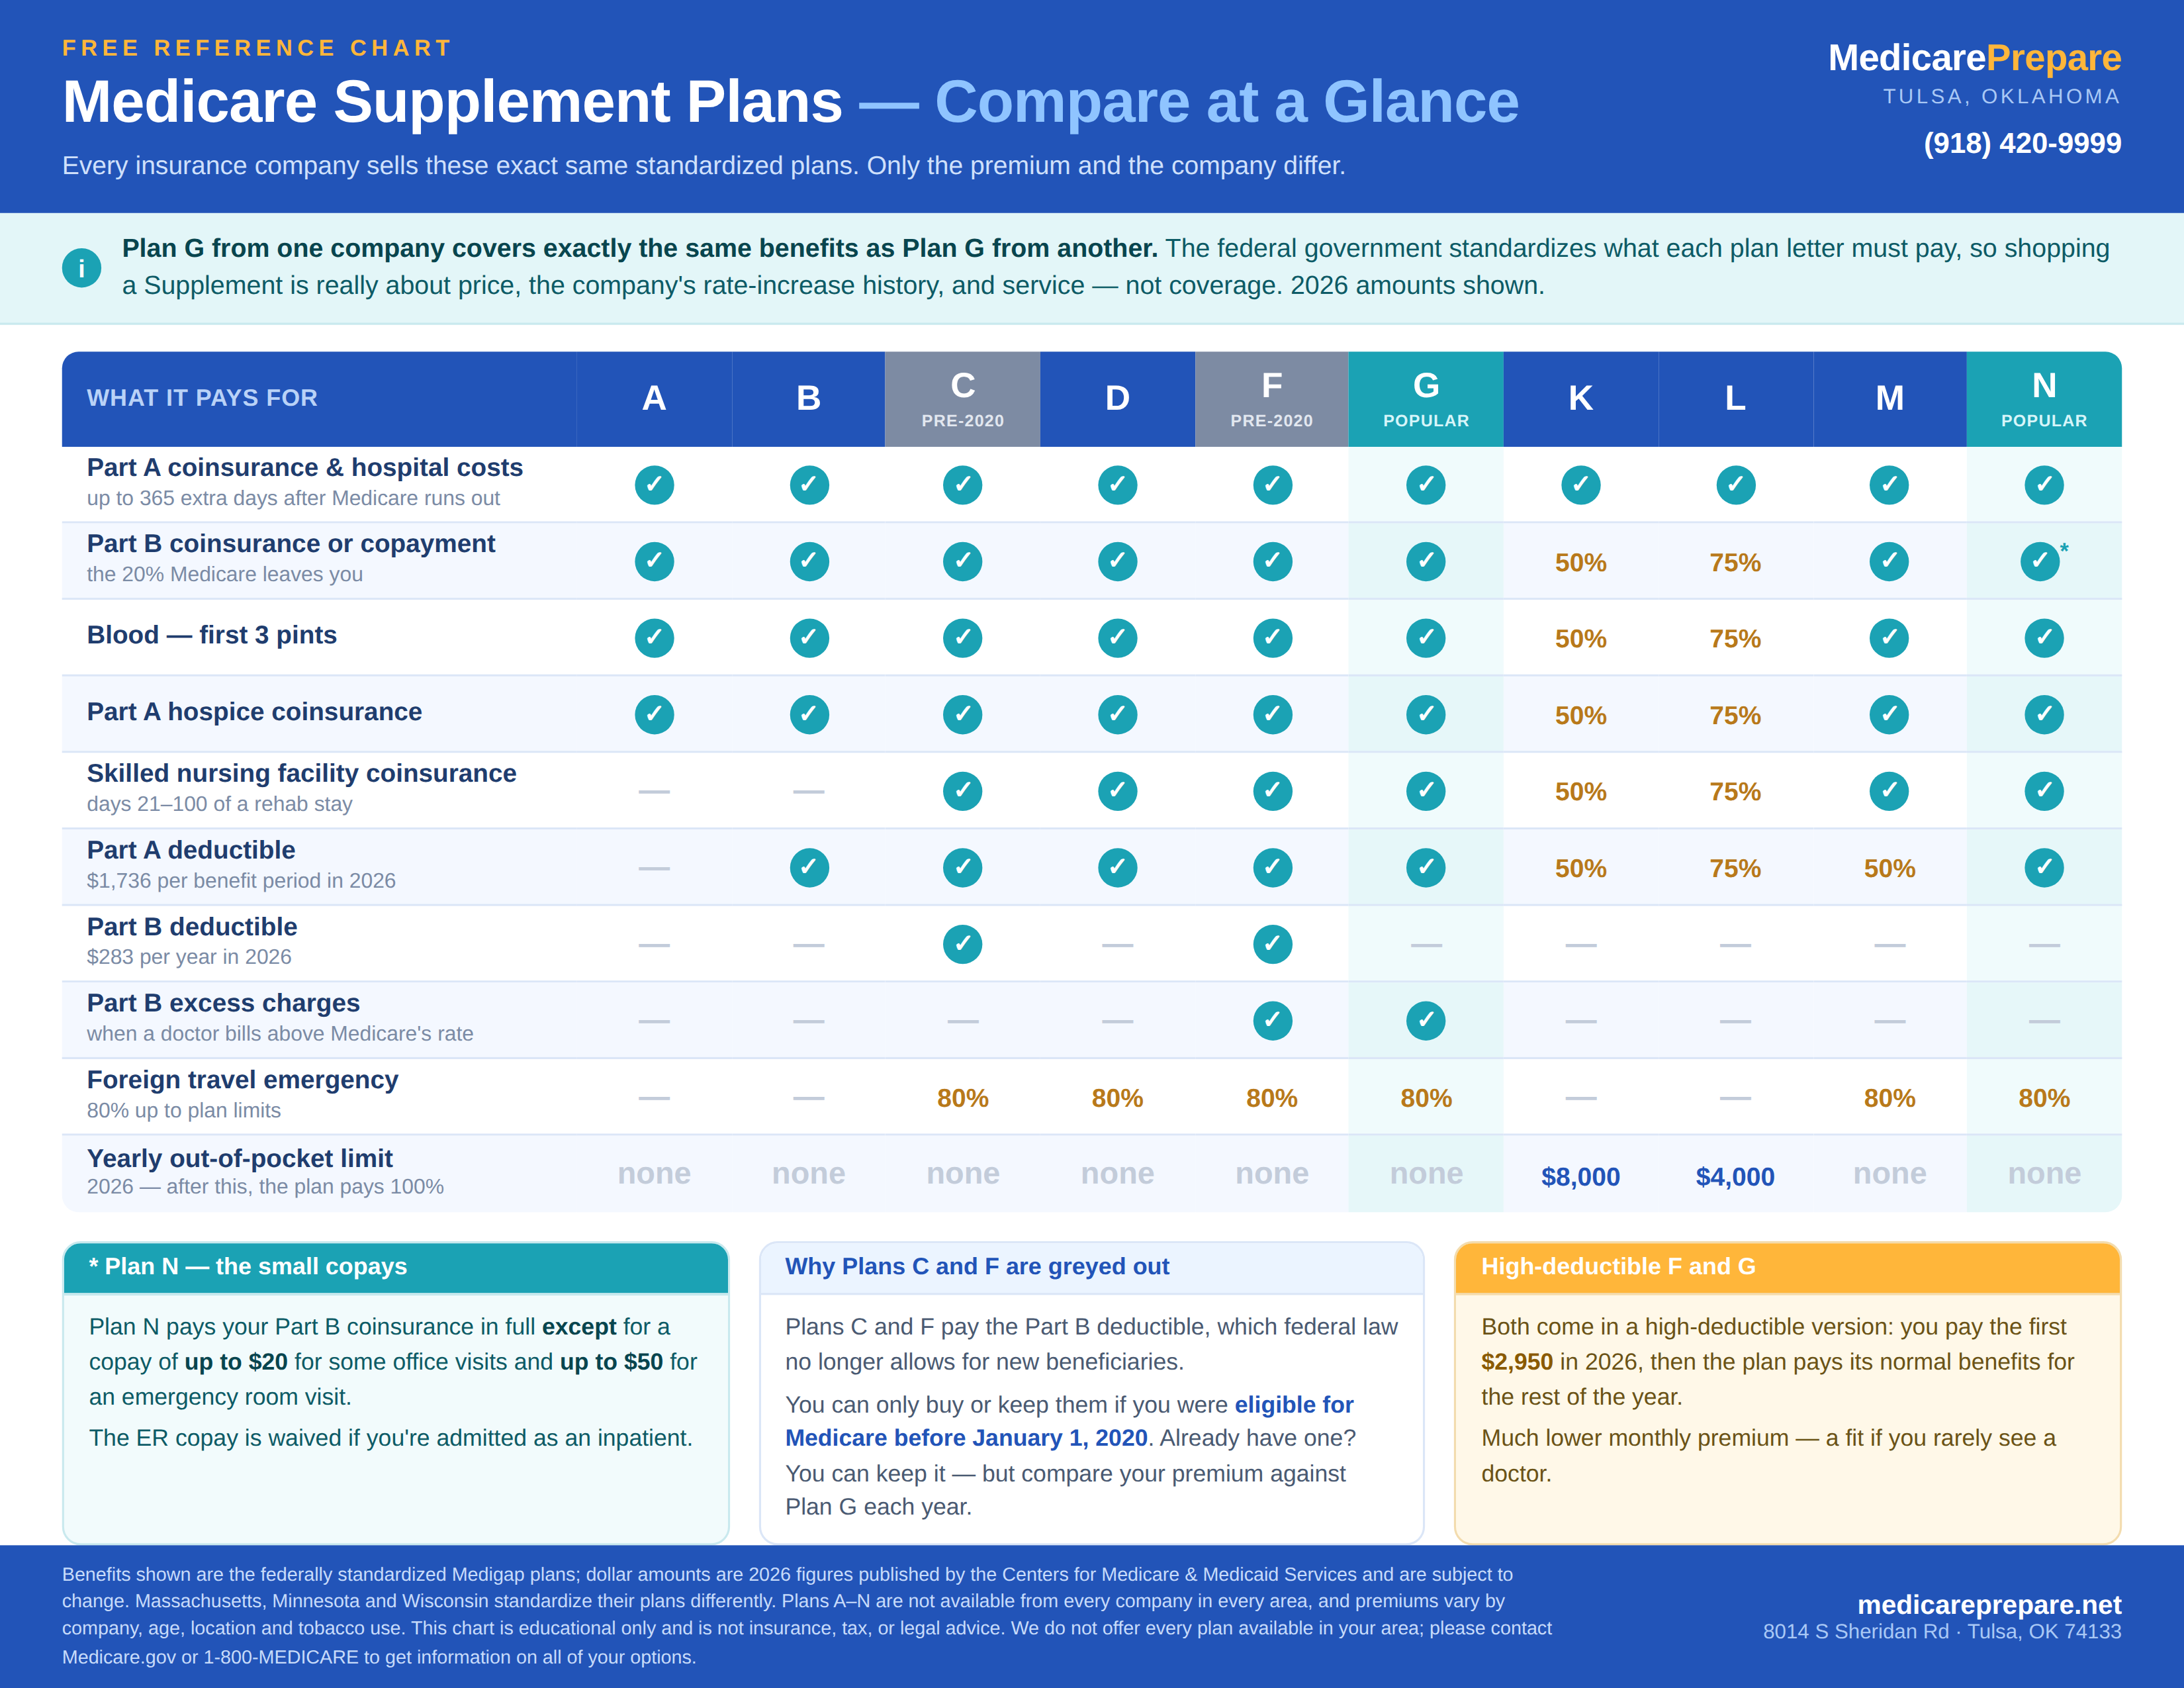
Plan G from one insurance company covers exactly the same benefits as Plan G from another. The letters (A, G, N, and a few others) are standardized by the federal government. The only real differences between companies are the premium, the customer service, and how they price rate increases over time. Shopping is about price and the company, not the coverage.
No networks, no referrals, nationwide
See any doctor or hospital in the country that accepts Medicare. No network to check, no referral to get, no prior authorization to wait on. That freedom is the trade-off for a higher monthly premium than a $0 Medicare Advantage plan.
Not Sure If a Supplement Fits? A 60-Second Self-Check
- See specialists often, or want to choose your own? A Supplement gives you that without a referral.
- Split time between two states, or travel a lot? Nationwide coverage matters more to you.
- Rarely see a doctor and want the lowest possible monthly bill? A $0-premium Advantage plan may fit better.
- Want the most predictable costs even in a bad health year? That is exactly what a Supplement is built for.
One phone call settles it. We will run the real numbers for your situation, plainly, and at no cost to you.
A Few Things Worth Knowing Before You Buy
Your best window is guaranteed, and it is short
For 6 months starting the month you turn 65 and enroll in Part B, you have Medigap Open Enrollment: any company must sell you any plan it offers, at its best price, no health questions asked. Miss that window and most states allow medical underwriting, meaning a company can charge you more, or turn you down, based on your health history. A few states protect you year-round. We will tell you plainly which rule applies where you live.
Under 65? You may still qualify
Federal law only guarantees Medigap coverage for people turning 65. Most states step in and require companies to sell to beneficiaries under 65 who qualified through disability or ESRD, but the rules vary widely: some guarantee it only during a short window after Part B starts, some let companies charge more, and a handful offer no protection at all. If you qualified for Medicare early, this is one of the first things we check for your state.
The birthday rule (or anniversary rule) lets some people shop every year
Missed your original window? Some states give you a second chance, every single year. Under a birthday rule you can switch to a different Medigap plan with equal or lesser benefits within 30 to 60 days of your birthday, no health questions asked. A handful of states use an anniversary rule tied to your policy's start date instead. Not every state has one, and the ones that do vary in how long the window stays open.
The Big Three: Plan F, Plan G, and Plan N
They all help fill the gaps left by Original Medicare, but there is one big reason you may not even be able to choose Plan F.
The grandfathered plan
Plan F covers essentially every Medicare-approved gap, including the Part B deductible, which is why it was once the most popular Supplement. It is now grandfathered: if you became eligible for Medicare before January 1, 2020, you may still be able to keep or buy it. Eligible on or after that date? Plan F is not available to you. Already on Plan F? As premiums rise, it is worth comparing what you pay against Plan G.
The most complete option for newer beneficiaries
Plan G is very similar to Plan F. The one difference: you pay the annual Part B deductible yourself. After that, Plan G covers the gaps it is designed to cover. It is often the first place we look for someone who wants predictable costs without the copays that come with Plan N.
Lower premium, a little more cost sharing
Plan N trades some monthly premium for a little more responsibility when you use care. You pay the Part B deductible and may have small office visit and emergency room copays, and Plan N does not cover Part B excess charges. For someone comfortable paying a little when they use coverage in exchange for a lower premium, it is worth comparing.
So which one is better?
There is no plan that is automatically best for everyone. The better question is: which plan gives you the right balance between what you pay every month and what you are comfortable paying when you actually use your health care? That is why we compare the numbers instead of simply recommending the plan with the most benefits or the lowest premium.
High-Deductible Plan G is the fourth option worth knowing: a much lower premium in exchange for paying a few thousand dollars yourself before it kicks in. A good fit if you rarely see a doctor and want the lowest possible monthly cost.
The trap: picking a plan by premium alone. People choose the cheapest option and get surprised later by copays or a deductible they forgot was coming. A five-minute conversation before you enroll prevents all of it.
Compare the Plans at a Glance
Freedom to Go Anywhere, Costs You Can Predict
A Supplement is the plan people choose when they want to keep the doctors they have, travel without worrying about networks, and know what a bad year would cost before it happens. We will show you the exact premium for each plan letter from every company we represent, plus what each one has done with rate increases over time.
Common Questions About Medicare Supplements
Can I really see any doctor with a Medicare Supplement?
Yes. If a doctor or hospital anywhere in the country accepts Medicare, they accept your Supplement. There is no network, no referral, and no prior authorization from the plan.
Why does my neighbor pay a different premium for the same plan letter?
Because the benefits are standardized but the prices are not. Each company sets its own premium and its own approach to rate increases, and premiums also vary by age, ZIP code, and tobacco use. That is why we compare companies, not just letters.
I missed my Medigap Open Enrollment. Can I still get one?
Often yes, but in most states the company can ask health questions and charge more or decline. Some states have birthday or anniversary rules that reopen a window every year, and certain situations (like losing an Advantage plan through no fault of your own) create guaranteed-issue rights. We check your state and your situation first.
Do I need a Part D plan with a Supplement?
Yes, if you want drug coverage. Supplements do not include prescription drugs, and going without creditable drug coverage for 63 days or more adds a permanent penalty later. Most of our Supplement clients pair it with a standalone Part D plan.
Can I have a Supplement and a Medicare Advantage plan at the same time?
No. A Supplement only works alongside Original Medicare. If you join an Advantage plan, the Supplement cannot pay on your claims, so you would choose one path or the other.
Stop guessing which plan fits.
In one complimentary conversation, we will compare Plan G, Plan N, and every other option against your budget and health needs, and tell you plainly which one makes sense and which one does not.
Claim Your Complimentary
Comprehensive Guide to Medicare!
Medicare can be a nightmare to understand. We've helped hundreds of Baby Boomers navigate this journey, and we hope this book can help you too!